 Tech News, Tech Iinfo Blog, Info Tech Blog
A network of hospitals and clinics with agreed-upon rates for insurance holders is how you can understand how preferred provider networks function in Singapore insurance terms.
How Singapore hospital preferred provider networks work
A hospital preferred provider network is a group of medical facilities that have signed a contract with your insurance company to provide services at specific, discounted rates. When you visit a hospital within this network, the insurer pays a larger portion of the bill, leaving you with a smaller co-payment or deductible. These arrangements are designed to manage healthcare costs while ensuring that patients have access to quality care at predictable prices.
Most people assume that being in a network means a hospital is “better” than one outside, but this is a financial arrangement rather than a quality ranking. If you have an integrated shield plan or a private health insurance policy, your provider network is defined by your specific policy document. It’s important to remember that these networks can change annually as contracts between insurers and hospitals expire or get renegotiated. You should always check your insurer’s official portal before booking a non-emergency procedure to confirm your chosen hospital is currently included.
How to use your medical network
Using your network effectively requires a few simple steps to ensure your insurance covers the maximum amount possible.
- Check your policy: Open your insurance summary to see if you have “panel” or “preferred” hospital access.
- Verify the current list: Log in to your insurer’s mobile app or website to view the most recent list of participating hospitals.
- Confirm the specialist: Even if the hospital is in-network, check that your specific doctor or surgeon is also part of the preferred list.
- Request a Letter of Guarantee: For planned surgeries, ask your hospital’s billing department to coordinate with your insurer for a Letter of Guarantee to confirm coverage before you check in.
- Present your card: Show your physical or digital insurance card at the registration desk so the staff can apply the correct billing rates.
- Review the discharge bill: Compare your final invoice against your policy’s “co-payment” or “deductible” clauses before making a final payment.
The decision to stay in-network versus going out-of-network is a trade-off between your choice of specialist and your total out-of-pocket expenses. If you prioritize a specific doctor who isn’t on your plan, you must be prepared to pay the difference between the hospital’s standard rate and your insurer’s allowed amount.
Essential network coverage figures
| Situation | Network Status | Expected Coverage | What to watch for |
|---|---|---|---|
| Emergency | Any Hospital | High (Regulated) | Check your policy for “emergency” definitions |
| Planned Surgery | In-Network | Highest | Ensure your specific doctor is also covered |
| Specialist Visit | In-Network | Standard | Check if a referral is needed for full payout |
| Specialist Visit | Out-of-Network | Low/None | High co-payment or full cost to you |
| Day Surgery | In-Network | High | Pre-authorization requirements |
Most patients assume “in-network” applies to the entire facility. This is a costly mistake. Even at an in-network hospital, an anesthesiologist or radiologist may be an independent contractor outside your plan. Always ask the billing office for the NPI numbers of your surgical team.
If you face an out-of-network bill, check your state’s balance billing laws. Many states now cap what providers can charge for surprise out-of-network care. If your state lacks these protections, negotiate the rate before the procedure.
Use this rule: If the service is elective, verify the provider’s status 72 hours before your appointment. If the service is urgent, prioritize safety first, then contact your insurer within 24 hours to initiate a claim review. This simple step often prevents a total denial of coverage. Never assume the hospital’s status covers every individual practitioner you encounter during your stay.
Keys to successful billing
Experienced patients know that the hospital registration desk is the best place to prevent billing surprises. Before you start any treatment, always ask the staff if your specific insurance plan is accepted at that facility. A common mistake people make is assuming all insurance plans work at every private hospital; this error can cost you thousands of dollars in unexpected “out-of-network” fees.
Experienced users also keep a record of all pre-approval codes provided by their insurer. If you’re having a procedure that requires multiple visits, confirm that the network status hasn’t changed between your first consultation and your follow-up surgery. Finally, leave the “billing disputes” to the professionals; if a charge seems wrong, don’t pay it immediately. Ask the hospital billing office to resubmit the claim with the correct insurance codes, as these errors happen frequently during data entry.
Troubleshooting billing issues
| What you notice | What it usually means | What to do first |
|---|---|---|
| Higher bill than expected | Wrong plan code used | Ask billing to re-verify your insurance card |
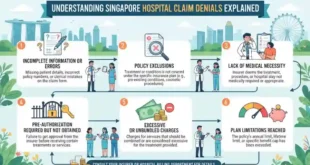
| Claim denied | Service not pre-authorized | Contact your insurer for the authorization log |
| Doctor listed as “out” | Only the hospital is in-network | Ask the hospital for an in-network alternative |
| “Excluded” service | Policy limits reached | Review your annual benefit cap |
Most billing errors stem from a mismatch between the provider’s NPI number and your specific network tier. If your bill remains high after verification, check if the provider used an “out-of-office” billing code. This happens when a doctor works at an in-network facility but bills through a private, out-of-network practice.
You can spot this by looking for a “facility fee” versus a “professional fee” on your Explanation of Benefits. If the professional fee is the culprit, ask the billing department to re-process the claim using the facility’s group tax ID.
Never pay the balance immediately. Doing so often counts as an admission of debt, making it difficult to claw back funds later. If the insurer insists the charge is valid, request a formal peer-to-peer review. This forces a medical director to justify the denial against your specific policy language.
Regulatory standards and limits
Healthcare providers and insurers in Singapore operate under guidelines set by the Ministry of Health. These rules ensure that basic healthcare remains accessible even if your specific preferred provider network doesn’t cover a facility. For example, emergency care is generally covered regardless of your network status, but the definition of “emergency” is strictly limited to life-threatening conditions. If you’re planning a surgery, you must follow the specific pre-authorization steps defined by your insurer’s policy. Failing to get this approval can result in a claim rejection, even if the hospital is in your network. Always consult your insurance agent or the human resources department if you have a group policy, as they can explain the exact limits of your coverage tiers.
Maintaining your coverage status
Once you have started a relationship with a specific provider, keep your insurance details up to date by notifying your hospital of any plan changes. Your coverage status is usually verified at every new visit, so don’t assume that a network status from last year still applies today. If your policy expires or you switch employers, your previous “preferred” status will end immediately.
Always carry your current insurance card and check the expiry date printed on it before going to a scheduled appointment. If you notice your insurer has removed your regular hospital from their network, you may need to find a new primary clinic to maintain your lower co-payment rates.
The most common mistake is assuming a referral remains valid after an open enrollment period. If you have changed plans, your old referral is likely void. If your new plan requires a primary care physician, confirm your specialist is still in-network before your next visit. If you’re unsure, call the member services number on your card to verify the specific billing code for your procedure.
Alternatives to network providers
If you find that your preferred hospital is no longer in your network, you have three main alternatives. First, you can choose a different facility that’s currently on your insurer’s preferred list to keep your costs low. Second, you can pay the higher out-of-network fees if the medical expertise at your chosen hospital is essential for your condition. Third, you can ask your insurer if they offer a “rider” or a “top-up” plan that expands your network access to include more facilities. Choosing the wrong facility can mean paying 20% to 50% more for the same procedure, so always compare the price lists provided by your insurer before moving forward with a non-emergency visit.
Frequently asked questions
Can I use my insurance at any hospital?
No, you’re generally limited to the hospitals listed in your policy’s preferred network for non-emergency procedures. While emergency care is typically covered everywhere, routine and planned surgeries outside your network will result in significantly higher out-of-pocket costs or a complete denial of your insurance claim.
How long does it take for a network list to change?
Network lists can change at the start of any calendar year, though some contracts update mid-year. You should check the official provider list on your insurer’s website at least 30 days before any scheduled appointment to ensure your chosen hospital remains an in-network provider for your specific plan.
Is it safe to go to an out-of-network hospital?
Yes, it’s medically safe, but it’s financially risky. The quality of care isn’t determined by your network status, but you’ll likely pay much more for the same services. Only choose an out-of-network hospital if the specific medical expertise you need isn’t available within your network.
What happens if my doctor leaves the network?
Your coverage for that doctor will stop immediately, and you’ll be billed at out-of-network rates. You should ask your doctor’s office if they plan to renew their contract with your insurer or if you should seek a referral to a new specialist who is currently in-network.
How do I check if my hospital is in-network?
You should log in to your insurer’s member portal or mobile app to search for your hospital by name. The most accurate data is always found through your insurer’s internal directory, rather than the hospital’s own website, because the insurer controls which plans they accept at each facility.
Can I get an exception for out-of-network costs?
Yes, some insurers allow exceptions if no in-network provider can perform your required procedure. You must request this “in-network exception” from your insurance provider in writing before your surgery, as they rarely grant these requests after the treatment has already been completed and billed.
Conclusion
If you find yourself confused by your specific policy, call the customer service number on the back of your insurance card before you book any medical appointment. They can confirm your network status in real time and tell you exactly what your co-payment will be for the procedure you need.