 Tech News, Tech Iinfo Blog, Info Tech Blog
Obtaining a singapore hospital insurance approval guide helps you understand the process of getting a Letter of Guarantee (LOG) or Pre-Authorization for your medical procedure. Most insurers require this step at least 3 to 5 days before elective surgery to ensure your coverage covers the specific treatment costs. This guide explains how to coordinate with your hospital and insurer to avoid unexpected out-of-pocket expenses when you check in.
Getting your hospital insurance approval
A pre-authorization or Letter of Guarantee is a formal document from your insurance company. It confirms they will pay the hospital directly for your treatment, up to a set limit. It’s used for planned hospital stays, such as surgeries or major procedures that require admission. For emergency cases, the process is different because you can’t wait for paperwork.
Hospitals don’t have access to your private insurance policy details. You must proactively initiate the request to bridge the gap between your insurer and the medical provider. If you skip this, you might have to pay the full bill upfront and wait weeks for a reimbursement claim. This isn’t for people seeking immediate, life-saving care; if you’re in an emergency, go to the nearest hospital and handle the insurance paperwork after you’re stabilized.
Steps to Secure Your Approval
- Consult your doctor: Ask your surgeon or specialist for the exact procedure code and the estimated total cost of the stay.
- Submit the form: Request the “Pre-Authorization Form” or “LOG Request Form” from your hospital’s admissions office or your insurance provider’s portal.
- Attach medical records: Provide your doctor’s referral letter or clinical notes that explain why the procedure is medically necessary.
- Send to insurer: Submit the completed paperwork to your insurer via their official app, portal, or email address.
- Wait for review: Most insurers process these requests within 3 to 5 business days, provided all clinical documentation is complete.
- Verify the LOG: Once approved, the hospital will receive a copy, but you should also keep a digital copy of the approval letter for your own records.
The critical judgement call is ensuring your clinical notes clearly justify the procedure. If the insurer finds the medical necessity unclear, they will delay the approval to request more information.
Essential Figures for Hospital Admissions
| Situation | Action Required | Typical Lead Time | What to Watch For |
|---|---|---|---|
| Elective Surgery | Submit Pre-Auth Form | 3-5 days | Policy sub-limits |
| Emergency Care | Present Insurance Card | Immediate | Deductible amount |
| Day Surgery | Request LOG | 48-72 hours | Panel provider status |
| Specialist Visit | Check Referral | 1-2 days | Co-payment rates |
| Overseas Treatment | Prior Approval | 7-10 days | Geographical limits |
When handling elective surgery, verify your policy sub-limits specifically for surgical implants and anesthesia. Many patients assume full coverage, only to find a 20% cap that leaves them with a surprise bill. If your procedure involves high-cost hardware, confirm the exact reimbursement tier before signing the consent form.
For emergency care, the primary mistake is failing to notify your insurer within 24 hours of admission. Even if the hospital accepts your card, delayed notification can lead to a denial of claims. Always designate a family member to call the insurer’s emergency line while you’re in triage.
If you’re scheduling day surgery, confirm the facility’s panel status at the moment of booking. A provider can drop from a network mid-year. If the facility is out-of-network, you’ll likely face a 30% increase in out-of-pocket costs. Always ask for the “Letter of Guarantee” (LOG) in writing to lock in your coverage rates.
Ensuring Success with Your Claim
Experienced patients know that the quality of your clinical documentation decides whether your request is approved on the first try. Your doctor must use specific medical terminology that aligns with your policy’s coverage definitions. If the diagnosis is vague, the insurer will likely pause the process to ask for clarification, which can delay your surgery date. Always confirm that your chosen hospital is a “panel” or “preferred” provider for your specific insurance plan.
Reviewing Policy Details
Check your policy documents for “co-payment” or “deductible” requirements. These are the portions of the bill you’re responsible for paying regardless of your insurance coverage. According to the Ministry of Health Singapore, understanding these cost-sharing mechanisms is vital for managing your medical expenses effectively. If you don’t verify these amounts before admission, you may face a surprise bill at discharge.
Troubleshooting Insurance Delays
| What you notice | What it usually means | What to do first |
|---|---|---|
| Approval status “Pending” | Missing clinical notes | Contact your doctor’s clinic |
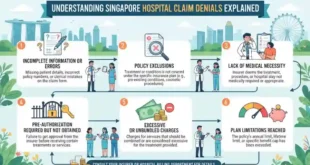
| Claim denied | Policy exclusion | Ask for a written reason |
| Incorrect bill amount | Deductible not applied | Check your insurance portal |
| Hospital says “No LOG” | Provider is off-panel | Call your insurance hotline |
When an approval stays pending for more than 72 hours, the issue is rarely the insurer. It’s almost always a missing fax or an incomplete diagnostic code from the physician’s office. Don’t wait for a notification. Call the clinic’s billing department and ask if they have received a “request for additional information.”
If you receive a denial for a policy exclusion, verify the decision against your Summary of Benefits. Many people mistakenly assume all denials are final. If the service was medically necessary, request an internal appeal immediately.
The most common mistake is paying a bill before the Explanation of Benefits arrives. Doing so often prevents you from catching errors where the provider failed to apply your negotiated rate. If the bill amount exceeds your deductible, hold payment for 30 days. This allows the electronic claims system time to reconcile the provider’s charges with your actual plan coverage.
Understanding Regulatory Thresholds
In Singapore, the regulatory framework ensures that insurance companies operate under strict guidelines set by the Monetary Authority of Singapore (MAS). These rules govern how insurers handle claims and how they communicate coverage changes to policyholders. If you feel an insurer is acting unfairly, you can approach the Financial Industry Disputes Resolution Centre (FIDReC).
Note that insurance doesn’t cover cosmetic procedures or experimental treatments. If your treatment falls into these categories, you’ll need to pay for the entire cost yourself.
A common mistake is assuming a doctor’s recommendation automatically triggers coverage. This is false. Insurers apply their own “medically necessary” criteria, which may differ from a surgeon’s clinical preference. If the insurer classifies your procedure as elective, they will deny the claim regardless of your physician’s note. Always verify with your insurer if your specific procedure is considered “medically necessary” before you book your surgery date to avoid unexpected out-of-pocket bills.
Maintaining Your Coverage Status
Once you have received your approval, keep digital and physical copies of your LOG until the final hospital bill is settled. If your surgery date changes, you must inform your insurer immediately; a new approval is often required for a different date.
After discharge, your insurer processes the final bill against the initial authorization. If the final cost exceeds the approved amount due to complications, the hospital contacts the insurer for a top-up approval. Don’t pay the hospital’s initial invoice if it arrives before your “Explanation of Benefits” (EOB) statement.
Monitor your insurance portal for these EOB statements, which show exactly what was paid and what remains as your responsibility. A common mistake is paying the hospital’s “balance due” statement before the insurer has finalized the claim. This often leads to overpayment for items already covered by your plan. If the EOB shows a lower balance than the hospital bill, use the EOB to dispute the charges with the hospital’s billing department.
When to Seek Alternative Funding
If your insurance doesn’t cover the full cost of a procedure, you may need to look at other ways to pay. Some procedures are covered under the government’s MediSave or MediShield Life schemes. You should check the Ministry of Health website to see if your specific condition qualifies for these subsidies.
Alternatively, some hospitals offer interest-free installment plans for self-paying patients. If you’re facing a large bill that insurance won’t touch, talk to the hospital’s financial counseling department before the procedure. They can often help you structure a payment plan or identify government assistance programs that you might be eligible for based on your income or residency status.
Many patients make the mistake of waiting until discharge to discuss costs. This limits your leverage. If you engage the finance office at least 72 hours before admission, you can often negotiate a fixed-price package. If your projected out-of-pocket expense exceeds 20% of your annual household income, ask specifically about means-tested subsidies.
Frequently asked questions
Can I get insurance approval on the same day as my surgery?
No, most insurers require at least 3 to 5 business days to review clinical documentation. Same-day approvals are generally only possible for emergency admissions where the hospital’s billing department works directly with the insurer’s emergency hotline.
What happens if the insurer denies my pre-authorization?
If your request is denied, the insurer will provide a letter explaining the specific policy clause or lack of medical necessity. You can work with your doctor to provide additional medical evidence or appeal the decision through the insurer’s formal appeals process.
Is it safe to proceed without an approved Letter of Guarantee?
It’s risky to proceed without an LOG because you become responsible for the entire hospital bill upfront. If the insurer later denies the claim, you’ll have to pay the full amount out of pocket without the benefit of direct billing.
How long does an insurance approval letter stay valid?
An approval letter is typically valid only for the specific date and procedure listed on the document. If your surgery is postponed by more than 7 days, you must contact your insurer to update the file and potentially get a new authorization.
How much will I have to pay for co-payment?
Your co-payment amount depends entirely on your specific insurance plan and the deductible you selected at purchase. You can find this exact figure in your “Schedule of Benefits” document or by logging into your insurer’s mobile app to view your current policy summary.
Conclusion
The process of securing insurance approval is a shared responsibility between you, your doctor, and your insurer. By starting the request early and ensuring your clinical notes are clear, you minimize the risk of financial stress during your recovery. Always keep copies of your communication with the insurer, as these are your primary evidence if a billing dispute arises after you leave the hospital.