 Tech News, Tech Iinfo Blog, Info Tech Blog
A singapore hospital panel hospital guide helps you identify which medical facilities are covered under your specific insurance plan to ensure you receive cashless treatment or lower out-of-pocket costs. Most private health insurance policies in Singapore require you to visit a listed facility to access direct billing services or pre-authorization. This information is vital because using an out-of-panel hospital often results in higher co-payments or a requirement to pay the full bill upfront before seeking reimbursement from your provider.
Choosing Your Singapore Hospital Panel Providers
A hospital panel is a list of healthcare institutions that have a formal agreement with your insurance provider. These networks are built to manage costs while ensuring that policyholders receive care within a standard quality framework. When you visit a panel hospital, the insurer often processes your claims directly, which simplifies the payment process during stressful medical situations.
Many people mistakenly believe that their insurance covers every hospital in the country equally. This is rarely true, as insurance plans often tier their coverage based on the facility’s status. If you visit a non-panel hospital, you might face a lower reimbursement rate or higher deductible requirements. Always verify your coverage status before scheduling non-emergency procedures. You can find the specific list of licensed healthcare institutions maintained by the Ministry of Health to understand which facilities are officially recognized in the national system, though your insurer’s specific panel list remains the primary document for your financial coverage.
How to Check Your Coverage
Follow these steps to confirm if a hospital is part of your network and how to proceed with your visit.
- Log in to your insurance provider’s official mobile app or web portal using your policy number.
- Navigate to the “Provider Search” or “Panel Hospital” section to view the current list.
- Select your specific plan name, as many insurers offer multiple tiers with different hospital access levels.
- Call the hospital’s admissions office to confirm they currently accept your specific insurance plan for the treatment you need.
- Obtain a Letter of Guarantee (LOG) from your insurer if your policy requires it for scheduled inpatient admissions.
- Bring your insurance card and a government-issued photo ID to the registration desk on the day of your appointment.
The most important decision you make is verifying your plan tier. If you choose a hospital outside your specific plan’s panel, you’ll likely pay the full cost upfront and wait weeks for a partial reimbursement. If the procedure is an emergency, go to the nearest hospital regardless of the panel status, as local regulations prioritize immediate life-saving care over billing agreements.
Essential Insurance Coverage Details
| Situation | Action Required | Typical Waiting Time | Financial Impact |
|---|---|---|---|
| Emergency | Go to nearest A&E | Immediate | Full coverage (usually) |
| Elective Surgery | Pre-authorization | 3-5 business days | Cashless with LOG |
| Specialist Visit | Referral from GP | 24-48 hours | Lower co-pay |
| Day Surgery | Panel verification | Instant | Minimal out-of-pocket |
For elective surgeries, failing to secure a Letter of Guarantee (LOG) before admission is a common mistake. Without this document, you may be forced to pay the entire hospital bill upfront and wait weeks for reimbursement. Always check your policy’s specific panel list first.
If your provider isn’t on the approved panel, your coverage often drops to 70% or less. Use the decision rule: if the procedure is non-urgent, confirm the surgeon’s panel status 72 hours before your appointment.
Emergency situations are exempt from these administrative hurdles. If you’re incapacitated, hospital staff will trigger the emergency protocol automatically. However, you must notify your insurer within 24 hours of admission to ensure the claim remains valid.
When seeking a specialist, ensure your GP referral is dated before the consultation. A referral issued after the visit is frequently rejected, leaving you responsible for the full specialist fee. Always verify the referral’s expiration date, as many are valid for only 30 days.
Maximizing Your Benefits
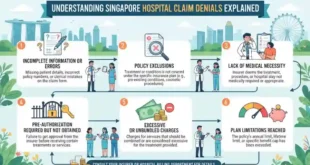
Experienced patients know that the secret to avoiding unexpected bills is the pre-authorization process. Even if a hospital is on your panel, the specific surgery or treatment might require prior approval from your insurer. Always ask your doctor’s office to submit the treatment plan to your insurer at least one week before a scheduled procedure. This prevents the “surprise bill” that occurs when an insurer decides a specific treatment wasn’t medically necessary or falls outside your policy limits.
If your insurer denies a request, don’t simply pay the invoice. Request the specific clinical guidelines they used to justify the rejection. Often, a peer-to-peer review between your doctor and the insurance medical director can reverse a denial if the office provides missing documentation.
Another detail often missed is the difference between an individual plan and a corporate plan. If you’re covered through your employer, your panel list might change if the company changes its insurance provider. Always check the digital portal rather than relying on a printed list from the previous year. If you’re changing jobs, ask HR for the updated provider network details immediately. Relying on an outdated directory can cost you thousands in out-of-network penalties.
Resolving Common Billing Issues
| What you notice | What it usually means | What to do first |
|---|---|---|
| Hospital requests deposit | Not on panel or no LOG | Call your insurance hotline |
| Higher co-pay than expected | Plan limit reached | Check your policy summary |
| Claim rejected | Non-covered procedure | Ask for a detailed report |
| Incorrect bill amount | Coding error | Request itemized statement |
When a hospital requests a deposit, don’t pay immediately. Verify your Letter of Guarantee (LOG) status first. If you pay out-of-pocket, reimbursement can take up to 90 days.
If your co-pay exceeds expectations, verify if you have hit your annual out-of-pocket maximum. Many patients assume their deductible resets in January, but some plans follow the fiscal year. Check your portal to confirm your specific cycle.
For rejected claims, don’t accept the initial denial. Ask the billing department for the specific CPT code used. If the code is correct but the claim remains denied, request a peer-to-peer review between your doctor and the insurance medical director.
Finally, never pay a bill that lacks an itemized breakdown. Generic “total balance” statements often hide administrative fees or double-billed supplies. If you find a discrepancy, submit a written dispute within 30 days to protect your credit score.
Navigating Regulatory Requirements
In Singapore, the Monetary Authority of Singapore (MAS) regulates the conduct of insurance companies, while the Ministry of Health (MOH) governs the quality of care provided by hospitals. Your insurance contract is a legal agreement that dictates exactly which services are covered and under what conditions.
If you believe a claim was unfairly denied, you can seek independent advice from the Financial Industry Disputes Resolution Centre (FIDReC). You must file your dispute within six months of receiving the final rejection letter from your insurer. Failing to meet this window forfeits your right to external mediation.
Never sign a document at a hospital that waives your right to contest a bill without reading it thoroughly. Many patients mistakenly sign “financial responsibility” forms that include arbitration clauses. If you see language requiring you to waive your right to a court hearing, cross it out before signing. This small action preserves your leverage during future insurance appeals.
Maintaining Your Policy Status
Keep your insurance documents digital and accessible. Most insurers now use mobile apps to host your e-card, which is often sufficient for admission to panel hospitals.
If you’re traveling or moving, ensure your policy is updated with your current contact information. Insurers send critical notices about network changes via email or SMS. Missing these alerts can lead to unexpected out-of-pocket costs if a previously covered facility leaves your network.
Review your coverage once per year during your renewal period. If your health needs have changed, such as requiring frequent specialist visits, you may need to upgrade your plan.
Use this simple decision rule: If your out-of-network claims exceeded 15% of your total medical spend this year, switch to a plan with a broader provider list. If your usage remained entirely within your current network, maintain your existing tier to avoid paying for unnecessary premium overhead.
When to Seek Alternative Care
Sometimes, the panel hospitals near you may have long waiting lists for specific specialists. In these cases, it’s often better to pay for a private consultation out-of-pocket rather than waiting months for a panel doctor. If you require highly specialized care that no panel facility offers, contact your insurer to request an “out-of-network exception.” This is a formal request where the insurer may agree to cover the cost at a non-panel hospital if no other option exists. Always get this approval in writing before committing to the service.
Is it safe to visit a non-panel hospital in an emergency?
Yes, it’s always safe to visit the nearest hospital during a medical emergency. Life-saving care is the priority, and most insurance policies include “emergency out-of-network” clauses that provide coverage when you can’t reach a panel facility due to the severity of your condition.
How long does it take to get a Letter of Guarantee?
It typically takes three to five business days to process a request for a Letter of Guarantee. You should submit your medical report and the estimated costs to your insurer as soon as your doctor confirms the need for a scheduled surgery.
Can I change my panel hospital list?
No, you can’t personally change the panel list, as it’s determined by the contract between your insurer and the healthcare providers. If you find your current list is inadequate, you should look for a different insurance plan that offers a broader network during your next renewal period.
What happens if my insurance card isn’t accepted?
If the hospital doesn’t accept your card, you’ll likely need to pay the bill yourself and file a manual claim. Ensure you keep all original medical reports, itemized receipts, and discharge summaries, as these are required by your insurer to process any reimbursement.
Why was my pre-authorization denied?
A denial usually means the proposed treatment isn’t covered under your specific plan terms or the insurer requires more clinical evidence. Contact your insurer’s claims department to understand the specific reason, and ask your doctor if they can provide additional documentation to support your case.
Your hospital panel is a dynamic list that changes based on provider contracts and insurance plan updates. Always verify your current network status through your insurer’s official portal before every hospital visit to ensure you remain within the coverage terms that protect your financial health.