 Tech News, Tech Iinfo Blog, Info Tech Blog
For most people in Singapore, the best health insurance for hospital care is an Integrated Shield Plan (IP) paired with MediShield Life — it covers public hospital care at a level you choose, and you can pay the rest from MediSave. The one case where a different route wins: if you’re a foreigner without a work pass, or you simply want cashless care at a private hospital, a standalone private hospital plan or an international plan fits better.
Comparing your hospital insurance options
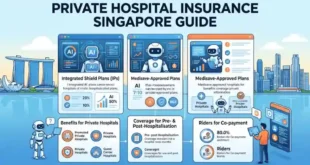
Singapore runs on a layered system. MediShield Life sits at the bottom for everyone, and Integrated Shield Plans sit on top. Here’s how the real options stack up.
| Method | How long to set up | Effort | Cost | Best for |
|---|---|---|---|---|
| MediShield Life only | Automatic from birth | None | Low | Basic public hospital bills, B2/C wards |
| Integrated Shield Plan (public hospital) | 1–2 weeks to apply | Low | Medium | Most Singaporeans wanting A/B1 wards |
| Integrated Shield Plan (private hospital) | 1–2 weeks to apply | Low | High | Private hospital care, choice of doctor |
| International/Expat plan | 2–4 weeks, medical checks | Medium | High | Foreigners, global coverage |
MediShield Life premiums come out of MediSave, so there’s no separate bill to track. IPs add a rider on top, and that rider is where the real cost difference shows up.
Costs here are words on purpose — the actual premiums depend on your age band and the insurer, and they change. Check the insurer’s own benefit schedule and the Ministry of Health’s IP comparison page for current figures.
How MediShield Life works on its own
MediShield Life is the national scheme every Singapore Citizen and Permanent Resident gets automatically. It’s run by the Central Provident Fund Board, and it never turns you away for a pre-existing condition.
- Check your ward class first. MediShield Life pays the most for B2 and C wards in public hospitals. In an A ward, the payout is capped at the B2 rate, so you pay the gap.
- Meet the deductible. You pay this amount each policy year before MediShield Life kicks in. It’s lower for C wards than for A.
- Pay the co-insurance. After the deductible, MediShield Life covers a share of the rest — you pay the co-insurance percentage.
- Claim through the hospital. Public hospitals submit the claim for you. You settle the balance at discharge.
The deductible and co-insurance reset every policy year, so a second admission in the same year starts the deductible again. That catches people out.
If you’re admitted more than once in a year, or your bill lands just above the deductible, the gap you pay is bigger than the first bill suggested.
Its strength is that it’s cheap, universal, and you can’t be rejected. The weakness is real: the annual claim limit and ward caps mean a long stay in a private hospital can leave you with a large bill.
Two things decide how much of that bill reaches you. The ward class sets the rate MediShield Life pays against. The deductible sets how much you clear before it pays anything at all.
Go to a B2 or C ward in a public hospital and the scheme does most of the work. Go private, or take an A ward, and you’re choosing to fund the difference yourself.
Adding an Integrated Shield Plan
An IP is a private plan that sits on top of MediShield Life. You buy it from an insurer, and it’s the piece most Singaporeans actually mean when they talk about hospital insurance.
- Pick your ward class. Public hospital IPs cover A or B1 wards. Private hospital IPs cover private hospitals and private doctors in public hospitals.
- Add a rider. The rider cuts your deductible and co-insurance, often to a fixed cap per year. Without it, you still pay a chunk.
- Pay from MediSave up to the limit. Part of the IP premium can come from MediSave, up to the Additional Withdrawal Limit. The rest is cash.
- Keep it active. Premiums rise with age. Miss a payment and cover lapses.
The upside is a much higher annual limit and access to private care. The honest weakness: riders now must carry a minimum co-payment, so “full cover” no longer exists. If you’re buying for the first time, ask the insurer to show you the co-payment rules in writing before you sign.
Going the international plan route
International health plans are built for people who move between countries. They’re common among expatriates and Singaporeans who work abroad part of the year.
- Apply with full medical disclosure. Expect a health questionnaire, and sometimes a medical exam.
- Choose your coverage area. Singapore-only, Asia, or worldwide excluding the US are the usual tiers. Wider means pricier.
- Pick a deductible level. A higher deductible lowers the premium, but you fund more of each claim yourself.
- Confirm direct billing. Check which Singapore hospitals bill the insurer directly, so you don’t pay upfront and wait for reimbursement.
These plans shine when you need cashless treatment and a wide hospital network. Their weakness is cost and underwriting — a new health condition can raise your premium or add an exclusion at renewal.
The coverage area you pick has to match where you actually spend your time, not where you might travel once. If you live in Singapore and take one trip a year, an Asia tier usually covers you. If you split the year between Singapore and Europe, or your job can post you anywhere, price the worldwide tier instead.
Direct billing isn’t a plan-wide feature. It’s granted hospital by hospital, and the list changes. Before any planned admission, call the hospital’s business office and ask whether your insurer is on their panel today. If it’s not, you pay the bill and claim it back, which can tie up a large sum for a while.
A deductible is charged per policy year, not per claim. Two small claims in January and March may both fall under it, and you pay for both.
Which one fits your situation
If you’re in a hurry — say you need cover before a scheduled procedure — go with an IP that has a short application window. Public hospital IPs usually process faster than private ones, and MediShield Life already covers you in the meantime. You won’t be uninsured while you wait.
If this is your first plan, start with a public hospital IP at the A or B1 ward level. It’s the middle ground: better than MediShield Life alone, far cheaper than a private hospital plan, and you can upgrade later if your income grows.
If you want the best result and cost isn’t the barrier, take a private hospital IP with a rider, or an international plan if you travel often. You get the widest choice of doctors and the shortest waits.
Here’s the trade-off in plain terms: every step up buys you more choice and comfort, and every step up costs more in premiums and in the share you still pay at the counter. There’s no plan that gives you both. The gap between what you pay and what you get back is the thing to watch, not the headline benefit.
What matters no matter which plan you pick
The rules don’t change with the plan. MediShield Life is administered by the CPF Board, and IPs are regulated by the Monetary Authority of Singapore, so any dispute or mis-selling complaint goes through official channels, not the insurer alone.
Before you sign, gather three things: your current ward preference, your budget for cash premiums after MediSave, and a list of any existing conditions. Declare every condition honestly — a hidden one can void a claim later, and that’s the most expensive mistake in this whole process.
Partway through, check two numbers: your annual claim limit and your co-insurance cap. If a hospital stay would blow past either, the plan isn’t doing its job for you.
At the end, review the plan every few years or after any big life change — marriage, a new baby, a chronic diagnosis. Premiums rise with age, so what fits at 30 may not fit at 55.
One limit worth naming: how much you’ll actually pay out of pocket depends on your ward class, your age band, and the insurer’s current rider terms. You can read your own numbers off the benefit schedule your insurer sends each year, or the Ministry of Health’s IP comparison tool.
Frequently asked questions
Is MediShield Life enough on its own?
For many people, yes — if you’re happy with B2 or C wards in a public hospital. It covers large bills and you can’t be rejected. But the ward caps and annual limit mean a private hospital stay or a long illness leaves a big gap. Most people add an IP to close that gap.
Can I use MediSave to pay for an Integrated Shield Plan?
Yes, but only up to the Additional Withdrawal Limit, which is set by the CPF Board and depends on your age. The rest of the premium is cash. Riders generally can’t be paid from MediSave at all — check the CPF Board’s current rules before you budget.
How long does it take to get covered?
An IP usually takes 1–2 weeks from application to approval, assuming you have no complex medical history. International plans take longer, often 2–4 weeks, because they need medical checks. MediShield Life covers you from birth or from the day you become a PR, with no waiting.
What happens if I have a pre-existing condition?
MediShield Life still covers you — it can’t exclude you. An IP or international plan can, though. The insurer may add an exclusion, charge a higher premium, or decline you. Declare everything; a claim denied for non-disclosure costs you far more than a higher premium.
Is it safe to buy a plan from any insurer?
Buy only from insurers. Check the insurer’s name on the MAS website before you pay anything. If an agent pressures you or promises “full cover” with no co-payment, walk away — that promise isn’t allowed anymore.
How often should I review my hospital plan?
Regularly, or after any major life event. Premiums rise with age bands, and rider terms change. A plan that was good value when you were younger can be expensive later. Reviewing takes an hour and can save you real money over the years.
Can foreigners buy hospital insurance in Singapore?
Yes. Foreigners on a work pass often get cover through an employer, but a personal international plan fills the gaps. Short-term visitors usually can’t buy local IPs. If you’re relocating, apply before you arrive — underwriting is easier when you have no local medical history.
Conclusion
Choosing hospital cover in Singapore comes down to one honest question: how much choice do you want, and how much are you willing to pay for it every year? MediShield Life answers the first part for everyone. The rest is a budget decision you make with your eyes open.