 Tech News, Tech Iinfo Blog, Info Tech Blog
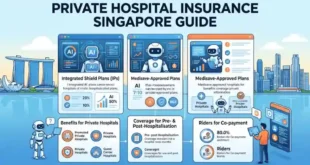
For most people in Singapore, the best hospital insurance setup is an Integrated Shield Plan (IP) paired with a rider, because MediShield Life alone leaves large bills for you to pay. An IP upgrades your ward class and lifts the yearly claim limit. The one case where a different method wins: if you’re a foreigner without a work pass, you’ll need an international or local private plan instead.
Comparing hospital insurance options in Singapore
An IP is the middle path most residents take, but it’s not the only one. The table below puts the real options side by side, so you can see where each one fits.
| Method | How long | Effort | Cost | Best for |
|---|---|---|---|---|
| MediShield Life only | Lifelong, auto-renewed | Very low | Low | Basic cover, subsidized wards |
| Integrated Shield Plan (IP) | Lifelong, while premiums are paid | Low | Medium | Most citizens and PRs |
| IP + rider | Lifelong, while premiums are paid | Low | High | People who want small cash outlay |
| International private plan | Yearly renewal | Medium | High | Expats, frequent travelers |
MediShield Life is run by the CPF Board and covers everyone, no matter your health. It pays for subsidized B2 and C class care, but the yearly limit and claim caps mean a big bill still leaves you paying part.
An IP is sold by private insurers and stacks on top of MediShield Life. It lets you choose a higher ward class, like A or B1. The premiums go up as you age, and the exact figures sit in each insurer’s own benefit schedule.
A rider is an add-on that cuts your deductible and co-insurance. That’s the part that usually stings. But riders now must carry a minimum co-payment, so no rider pays 100% anymore.
International plans are for people outside the MediShield Life system. They cost the most and renew each year. For the exact rules on who qualifies, check the CPF Board’s own pages.
How MediShield Life works
MediShield Life is the base layer every Singapore citizen and PR has. You don’t apply for it — it starts automatically and you can’t be rejected for health reasons. Premiums come out of your CPF MediSave, and the government adds support for lower-income households.
Here’s how a claim runs:
- You’re admitted to a restructured hospital in a subsidized ward (B2 or C class).
- The hospital submits the bill to CPF Board after you’re discharged.
- MediShield Life pays its share, after the deductible and co-insurance.
- You pay the rest, which you can cover with MediSave.
The deductible is the amount you pay first each year before MediShield Life kicks in. Co-insurance is your share of the rest. Both are set by CPF Board, and the exact amounts depend on your ward class and age.
What it’s good at: it never turns you away, and it covers pre-existing conditions from day one. That’s a real safety net.
Its weakness is the ceiling. Claim limits and ward-class rules mean a long stay in a higher-class ward, or a costly private treatment, leaves a big gap. If you want that gap closed, MediShield Life alone won’t do it.
How an Integrated Shield Plan works
An IP is private insurance that sits above MediShield Life. You buy it from an insurer, and it raises your yearly claim limit and lets you pick a higher ward class. You still keep MediShield Life underneath — the IP just adds to it.
The steps to set one up:
- Pick your ward class: B1, A, or private hospital.
- Compare insurers on claim limits, panel hospitals, and exclusions.
- Apply, and declare your health honestly on the form.
- The insurer may ask for a medical check or exclude a condition.
- Pay the premium — part can come from MediSave, up to the CPF withdrawal limit.
Premiums rise with age, and they rise in steps. A plan that’s cheap at 30 costs much more at 60. Each insurer publishes its own premium table, so check the numbers there, not from a friend.
What it’s good at: it covers the gap MediShield Life leaves, and you get more choice of hospital and doctor.
Its weakness: you can be rejected or have conditions excluded if you have health issues when you apply. And premiums keep climbing. If you have a serious pre-existing condition, an IP may not be open to you at all — talk to a licensed financial adviser who can explain your options.
How a rider changes your bill
A rider is an add-on to your IP. It reduces the deductible and co-insurance you’d otherwise pay. Without a rider, you cover those two amounts yourself; with one, the insurer covers more of them.
How it works:
- Add the rider to your existing IP at the same insurer.
- Pay the rider premium, which is separate from your IP premium.
- When you claim, the rider cuts your deductible and co-insurance.
- You still pay a minimum co-payment — this is required now.
That last point matters. The Ministry of Health introduced a minimum co-payment rule for new riders, so no rider pays the full bill. You always carry some of the cost. That keeps premiums from spiraling.
What it’s good at: it makes your out-of-pocket cash small for most bills, and it’s simple to add.
Its weakness: the extra premium adds up over decades, and for some people the total paid in premiums is more than the bills they’d ever claim. If your IP already covers most of what you’d face, a rider may not be worth it.
A fourth option — an international private plan — is rarely worth it for residents. It costs the most and renews yearly. It only makes sense if you live outside the MediShield Life system or travel constantly.
Which plan fits your situation
If you’re in a hurry and just need cover now: go with MediShield Life alone, or add an IP if you’re healthy. MediShield Life starts automatically, so you’re never uncovered. An IP takes a few days to a couple of weeks to approve, depending on the insurer and any medical checks.
If you’re doing this for the first time: start with an IP at a B1 or A ward class. It’s the middle path — more cover than MediShield Life, less cost than a private-hospital plan. Read the exclusions carefully before you sign.
If you want the best possible result whatever it takes: an IP for private hospitals plus a rider. You get the widest choice of doctors and the smallest cash bill. You’ll pay the highest premiums, and they’ll keep rising with age.
The trade-off is always the same: more cover now means more premium later, and no plan pays everything. Cheap today usually means a bigger gap when you claim. The right pick depends on your age, your health, and how much premium you can carry for decades.
What matters no matter which plan you pick
Whichever route you take, a few things stay the same.
The rules come from named bodies. MediShield Life is run by the CPF Board, and private IPs are regulated by the Monetary Authority of Singapore. The Ministry of Health sets the ward-class and co-payment rules. For the exact current figures, read each body’s own published guidance — don’t rely on what someone told you.
Prepare before you apply. Gather your medical history and be honest on the form. A missed condition can void a claim later. Check the CPF Board’s MediShield Life page for how the base layer works.
Check partway through. Read the exclusions, the panel hospitals, and the premium table. Confirm what’s covered and what isn’t before you commit.
At the end. Keep your policy documents, and review your plan every few years. Premiums and your health change, so what fit at 30 may not fit at 50.
If your case involves a serious health condition or a large sum, a licensed financial adviser handles it properly — not a forum post.
Two details trip people up more than any others.
The first is the panel. A private IP usually pays in full at its own panel hospitals and doctors, and only partially elsewhere. If you want to keep seeing a doctor outside the panel, check the reimbursement rate before you sign, not after.
The second is the base layer. MediShield Life covers everyone, including those with existing conditions, and no one is turned away. An IP sits on top of it and doesn’t replace it.
If you’re healthy and weighing an upgrade, compare the premium against what you would actually pay out of pocket at a restructured hospital.
Frequently asked questions
Is MediShield Life enough on its own?
For subsidized B2 or C class care, often yes. For higher ward classes or private hospitals, no — the claim limits and ward rules leave a gap you pay yourself. If you want that gap closed, you’d add an Integrated Shield Plan. Check CPF Board’s current limits to see where you stand.
Can I have both MediShield Life and an Integrated Shield Plan?
Yes. An IP is built on top of MediShield Life, not instead of it. You keep MediShield Life as the base, and the IP adds higher limits and ward-class choice. You pay for both, though part of the IP premium can come from MediSave up to the CPF withdrawal limit.
How long does it take to get an Integrated Shield Plan approved?
Usually a few days to about two weeks, depending on the insurer and whether they ask for a medical check. If you declare a health condition, it can take longer while they assess it. The insurer will tell you its own timeline when you apply.
Why was my Integrated Shield Plan application rejected?
Most often because of a pre-existing health condition the insurer won’t cover. Insurers can reject you or exclude specific conditions. If that happens, you still have MediShield Life, which can’t reject you. A licensed financial adviser can explain what else might be open to you.
Is it safe to drop my rider to save money?
It’s allowed, but you’ll pay more cash when you claim, because the rider was cutting your deductible and co-insurance. Dropping it lowers your premium but raises your out-of-pocket cost. Weigh both before you cancel, and check your insurer’s current terms first.
What happens if I stop paying my IP premium?
The policy can lapse, and you’d fall back to MediShield Life only. If you lapse and later want to rejoin, you may face new health checks and exclusions. Premiums can also rise. Keep payments current, or talk to your insurer before you stop.
How often should I review my hospital insurance?
Review your plan whenever your health, age, or job changes. Premiums rise in steps with age, and your needs shift. A quick review keeps you from paying for cover you don’t need — or missing cover you do.
Conclusion
The right hospital insurance comes down to how much gap you’re willing to carry and how much premium you can pay for years. Start with MediShield Life as your base, then add an IP if you’re healthy and want more. Read every exclusion before you sign, and revisit the plan as your life changes.