 Tech News, Tech Iinfo Blog, Info Tech Blog
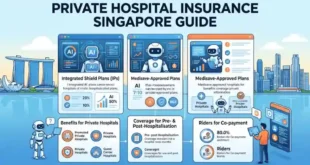
In Singapore, the best hospital insurance is an Integrated Shield Plan (IP) paired with MediShield Life. MediShield Life covers everyone, including pre-existing conditions, while an IP adds private or A-class ward coverage through insurers like AIA, Great Eastern, Income, Prudential and Singlife. Premiums rise with age, so the right choice depends on your ward class and budget. This guide covers how the plans work, what they cost, and how to pick one.
What Hospital Insurance in Singapore Really Is
Hospital insurance in Singapore is a two-layer system. The first layer is MediShield Life, a basic national plan run by the Central Provident Fund (CPF) Board that every Singapore Citizen and Permanent Resident holds for life. It pays for subsidized care in public hospitals, with limits on what it covers.
The second layer is an Integrated Shield Plan. A private insurer runs it, and it stacks on top of MediShield Life. An IP raises your claim limits and lets you choose a higher ward class, such as A or B1 in a public hospital, or a private hospital.
You pay for an IP with a mix of MediSave and cash. The MediShield Life portion comes from MediSave, and the extra rider usually needs cash.
The common misconception is that an IP covers everything. It doesn’t. Every plan has a deductible and a co-insurance share, and riders that once wiped these out now must carry a minimum co-payment.
How to Choose a Hospital Insurance Plan
Choosing well comes down to matching the plan to the ward class you’d actually use, then checking the fine print on exclusions and riders. Work through these steps in order.
- Set your ward class. Decide between private hospital, public A, public B1, or staying on MediShield Life only. This single choice drives everything else.
- Compare claim limits. Look at the annual and lifetime limits for each plan. A private hospital plan needs higher limits than a B1 plan.
- Check the deductible and co-insurance. For public A ward, the deductible is often around S$2,000–S$3,500 a year. For private hospital care, it’s higher. Confirm the exact figure in the plan’s product summary.
- Add a rider, if it fits. A rider lowers your out-of-pocket share but adds premium. Since 2021, new riders must carry a co-payment of at least 5%, so no rider removes your share entirely.
- Check exclusions and waiting periods. Most plans exclude pre-existing conditions for a set period, often 12 months or more. Read the list before you sign.
- Confirm the premium schedule. Premiums rise with age, and they jump sharply after 60. Ask for the full age-band table, not just today’s price.
- Pay the first premium and check your MediSave balance. Make sure your MediSave can cover the MediShield Life portion so you don’t pay cash for it.
The judgement call that matters most is the ward class. Pick a class you’d genuinely accept in an emergency, not the one that looks best on paper. A private hospital plan you can’t sustain past 65 leaves you downgrading later, often when health issues make switching harder.
If your situation involves a complex medical history or you’re weighing a large sum, a licensed financial adviser can review your options properly. This guide can’t replace that.
Hospital Insurance Numbers to Compare
Use this table to line up the main plan types. Premiums and limits change often, so treat the figures as a starting point and confirm current numbers with each insurer or CPF Board.
| Situation | What to use | How long | What to watch for |
|---|---|---|---|
| Healthy, want basic cover | MediShield Life only | Lifelong | Lower limits, subsidized wards only |
| Want public A ward | IP with A-class cover | Until you stop paying | Deductible around S$2,000–S$3,500 a year |
| Want public B1 ward | IP with B1 cover | Until you stop paying | Lower premium, still above MediShield |
| Want private hospital | IP with private cover | Until you stop paying | Highest premiums, steepest age rises |
| Have a pre-existing condition | MediShield Life, then apply for IP | Lifelong for MediShield | IP may exclude the condition |
| Over 60 | Review your current IP | Annual review | Premiums rise sharply in this band |
| Want lower out-of-pocket | IP plus a rider | Until you stop paying | Rider must carry at least 5% co-payment |
What Separates a Good Plan From a Bad One
The difference rarely shows up in the brochure. It shows up in the details people skip.
Experienced buyers read the exclusions list first. They check how the plan treats pre-existing conditions, congenital issues, and specific treatments. They also check whether the plan covers community hospital care and day surgery, not just inpatient stays.
They look at the premium table across every age band, not just their current one. A plan that’s cheap at 40 can become hard to hold at 70. Knowing that curve in advance stops a nasty surprise later.
Preparation and order of work
Smart buyers gather their medical history before applying. They declare conditions honestly, because a non-disclosure can void a claim years later. They apply while healthy, since a new diagnosis can lead to exclusions or a rejection.
They also compare at least three insurers side by side, using the same ward class each time. Comparing a B1 plan against a private plan tells you nothing useful.
What to leave alone
Don’t switch plans every year chasing a lower premium. A new plan resets your waiting periods and can re-exclude conditions you already have. Stick with a plan unless there’s a real reason to move, and get advice before you do.
Common Problems and Quick Fixes
Most issues come down to a handful of causes. Here’s how to read them.
| What you notice | What it usually means | What to do first |
|---|---|---|
| Claim rejected | Condition was excluded or not declared | Check your policy’s exclusion list and your application |
| Big bill after discharge | Deductible and co-insurance not met | Review your rider and co-payment terms |
| Premium jumped | You moved into a higher age band | Check the insurer’s premium table |
| Can’t use MediSave fully | Plan exceeds MediSave withdrawal limits | Check the CPF Board’s current limits |
| Want to switch plans | New plan may reset waiting periods | Get advice before cancelling the old plan |
The Rules That Apply
MediShield Life is mandatory for all Singapore Citizens and Permanent Residents, and you can’t opt out. The CPF Board runs it and sets the premiums and claim limits. You can check the current figures on the CPF Board’s site.
Integrated Shield Plans are regulated by the Monetary Authority of Singapore, and the Ministry of Health sets the coverage rules they must follow. Since 2021, new IP riders must include a co-payment of at least 5% of the claimable amount, so no rider covers 100% of a bill.
MediSave can pay for part of your IP premium, but only up to set limits based on your age. Anything above that limit comes from cash.
If you’re unsure whether a plan suits your health situation, speak to a licensed financial adviser. This guide explains the system, but it can’t assess your medical history or tell you which plan to sign.
Keeping Your Cover Working
Once your plan is in place, a little upkeep keeps it useful. Pay premiums on time so the policy doesn’t lapse, and keep your MediSave topped up to cover the MediShield Life portion.
Review your plan once a year, ideally before your birthday, since premiums change by age band. Check that your ward class still matches what you’d want, and that your rider still fits your budget.
Keep your policy documents and claim records in one place. If you change jobs or your family situation changes, check whether your dependants are covered.
If you’re hospitalized, submit claims promptly and keep every receipt and discharge summary. Missing paperwork is one of the most common reasons a claim gets delayed.
When Hospital Insurance Isn’t the Right Answer
An IP isn’t right for everyone. If your budget is tight and you’re healthy, MediShield Life alone covers subsidized public care, and it’s better than stretching for a plan you can’t maintain.
If you’re near retirement and premiums are climbing fast, a lower ward class plan may serve you better than a private one. Downgrading on your terms beats lapsing later.
If you have a serious pre-existing condition, a new IP may exclude it entirely. In that case, staying on MediShield Life, which covers pre-existing conditions, is often the safer path. Speak to an adviser before you decide.
Frequently asked questions
Is hospital insurance in Singapore mandatory?
An Integrated Shield Plan is optional. You choose whether to buy one, and you can drop it later if your budget changes, though you’d lose the extra coverage.
How much does hospital insurance cost in Singapore?
It depends on your age and ward class. MediShield Life premiums start low for young adults and rise with age. IP premiums are higher and rise sharply after 60. Check the CPF Board and each insurer’s current premium tables, since figures change.
Can I use MediSave to pay for hospital insurance?
Yes, but only up to set limits based on your age. MediSave covers the MediShield Life premium in full and part of your IP premium. Anything above the withdrawal limit comes from cash. Check the CPF Board’s current limits.
What happens if I don’t declare a pre-existing condition?
Your claim can be rejected, and the insurer may cancel your policy. Non-disclosure is one of the most common reasons claims fail. Always declare your full medical history when you apply, even if a condition seems minor or long resolved.
How long do I have to wait before a new plan covers me?
Most IPs have a waiting period, often around 90 days for general conditions and longer for specific ones like pregnancy or certain illnesses. Pre-existing conditions are usually excluded for a set period or permanently. Check your plan’s exact terms.
Is it safe to switch hospital insurance plans?
It’s possible but risky. A new plan resets your waiting periods and may exclude conditions you already have. Never cancel your old plan before the new one is approved. Speak to a licensed adviser before switching.
Why did my premium go up?
Premiums rise with age, and insurers also adjust them when medical costs climb. Moving into a higher age band is the usual reason. Check your insurer’s premium table to see the full curve, not just the current year.
Conclusion
The right hospital insurance plan comes down to the ward class you’d genuinely use and the premium you can sustain for decades. Compare a few insurers at the same ward class, read the exclusions, and check the age-band premium table before you commit. MediShield Life covers everyone, so an IP is about comfort and choice, not basic protection. Review it once a year, and get advice if your health or budget changes.