 Tech News, Tech Iinfo Blog, Info Tech Blog
If you’re a Singapore citizen or PR and your hospital bill is more than you can pay, you can apply for help — and you won’t be turned away for lack of money. The main routes are MediFund, MediShield Life, and the hospital’s own medical social worker. This Singapore hospital financial assistance guide walks you through each one, who qualifies, and what to bring.
What hospital financial assistance really means
Hospital financial assistance in Singapore is a set of government schemes and hospital-run programs that help you pay a bill you can’t cover yourself. Nobody is refused emergency care because they can’t pay. The schemes exist to make sure of that.
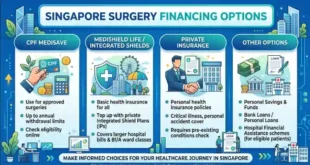
The system works in layers. MediShield Life, run by the CPF Board, is basic health insurance that every citizen and PR has. It pays part of large bills automatically, and you never apply for it. MediFund is the safety net under that — government money given through the hospital when MediShield Life and your own cash still aren’t enough. On top of both, each public hospital has medical social workers who can tap extra funds.
The common misconception is that you must be very poor to get anything. That’s wrong. MediFund looks at your income, your bills, and what you’ve already used. A middle-income family hit by one big unexpected bill can qualify.
The one rule to remember: you ask the hospital, not a government office. Every application runs through the medical social worker at the hospital where you were treated.
How to apply, step by step
The process is the same at every public hospital. Start early — before the bill is due, not after. Here’s what to do.
- Tell the hospital you need help. Ask any staff member for the medical social worker (MSW). At A&E, say it at the counter. You can also call the hospital’s general line and ask for Medical Social Services.
- Book an appointment with the MSW. Bring your NRIC, your spouse’s NRIC, and your latest bill. If you’re applying for someone else, bring proof you’re their caregiver.
- Gather income documents. Bring your latest payslips (usually the past 3 months), your CPF contribution history, or a letter from your employer. If you’re self-employed, bring your latest tax notice.
- Fill in the application form. The MSW helps you. You’ll list your household members, their income, your savings, and any property you own.
- Wait for the assessment. The MSW checks your MediShield Life claim first, then your income, then your MediFund eligibility. This usually takes a few working days.
- Get the decision in writing. You’ll be told how much is covered and how much you still owe. Ask for it in writing so you can plan.
- Set up a payment plan for the rest. If a balance remains, the hospital can split it into monthly installments. Ask about this before you leave.
The one judgement call that matters most: apply before the bill goes to collections. Once a debt is passed to an external agency, the hospital has less room to help, and you lose options.
If your case involves a legal dispute — like a workplace injury claim or a motor accident claim — that’s not a hospital matter. Talk to a lawyer or the relevant authority instead.
Key numbers and help you can get
The table below covers the main situations you’ll face. Use it as a quick reference when you’re deciding what to apply for.
| Situation | What to use | How long | What to watch for |
|---|---|---|---|
| Small bill, some cash savings | MediShield Life claim only | Days to process | Check your deductible — you pay this first |
| Big bill, low income | MediFund via hospital MSW | A few working days | Bring 3 months of payslips |
| Big bill, middle income | MediFund + installment plan | 1-2 weeks | Ask about the payment plan early |
| Elderly parent, no income | MediFund + Medifund Silver | 1-2 weeks | Parent must be a citizen |
| Chronic illness, ongoing costs | MediFund + Community Health Assist Scheme | Ongoing | Apply once, renew yearly |
| Foreigner or non-PR | Hospital’s own charity fund | Varies by hospital | Very limited — ask MSW first |
| Can’t pay at all | MSW + hospital waiver | Case by case | Never ignore the bill |
MediFund Silver is a separate scheme for needy elderly Singaporeans. It’s run through the hospital too, so ask the MSW about it if your parent is over 65.
What makes an application succeed
The strongest applications are the ones where the paperwork arrives complete and on time. The MSW has many cases, so a file with missing payslips sits at the bottom of the pile. Bring everything at the first appointment.
Experienced applicants also ask about MediShield Life before MediFund. Your insurance claim always runs first — MediFund only covers what’s left. If you skip that step, your MediFund assessment gets delayed while the hospital waits for the insurance figure.
Timing and order matter
Apply within the same month as your discharge if you can. Bills that are still fresh are easier to adjust than ones already overdue. If you know a big procedure is coming, talk to the MSW before the surgery, not after.
What to leave alone
Don’t pay a large lump sum “to show good faith” before your assessment. That money could have covered your share after MediFund, and getting it back is slow. Tell the MSW what cash you have and let them work the numbers.
Common problems and quick fixes
Most delays come from missing documents, not from being rejected. Here’s how to match what you’re seeing to what to do.
| What you notice | What it usually means | What to do first |
|---|---|---|
| Application stuck for weeks | Missing income proof | Call MSW, ask what’s missing |
| Bill still growing | MediShield claim not filed | Ask hospital to file it now |
| Told you earn “too much” | Assessment used gross income | Ask about household size adjustment |
| Partial approval only | Savings or property counted | Ask MSW to review with you |
| Collector calling | Bill passed to agency | Call hospital MSW the same day |
If a debt collector is already involved, don’t wait. Hospitals can sometimes pull a case back if you engage quickly. The longer it sits, the harder that becomes.
The rules and who sets them
MediFund is governed by the MediFund Act, and the Ministry of Health (MOH) sets the income criteria and payout rules. Each public hospital applies those rules through its own Medical Social Services department, so the exact help can differ slightly between hospitals. MOH publishes the current eligibility framework on its website.
MediShield Life is administered by the CPF Board. It’s compulsory for all citizens and PRs, and you can’t opt out. The CPF Board publishes the claim limits, deductibles, and co-insurance rates — check those pages for the current figures, since they change.
For the MediFund framework and current income criteria, see the Ministry of Health MediFund page.
If your situation involves a legal claim, a work injury, or an insurance dispute, that’s outside the hospital’s scope. Speak to a lawyer or the relevant authority — the MSW can point you but can’t act for you.
After you get approval
Once your application is approved, keep every letter. Save the approval letter, the payment plan, and the final bill together in one folder, physical or digital. If a new bill arrives later, you’ll need those to show what was already covered.
Most approvals cover the current episode of care, not future ones. If you’re treated again for the same condition, you may need to reapply. Ask the MSW whether your approval is one-time or ongoing — that answer changes what you do at the next visit.
Keep paying any installment plan on time. A missed payment can cancel the plan and send the balance back to collections. If your income drops, tell the MSW before you miss a payment, not after.
When this approach won’t work
Three situations where hospital financial assistance isn’t the right route:
If you’re not a citizen or PR, MediFund and MediShield Life don’t apply to you. Only the hospital’s own charity funds might help, and those are limited. Ask the MSW directly.
If your bill comes from a private hospital, the government schemes mostly don’t cover it. You’d need to transfer to a public hospital or negotiate directly with the private one.
If your problem is a legal claim — a workplace injury, a traffic accident, a malpractice dispute — the money should come from that claim, not from MediFund. Get legal advice first.
Frequently asked questions
Can I get help if I’m not a Singapore citizen?
No, MediFund and MediShield Life are for citizens and PRs only. Foreigners can ask the hospital’s medical social worker about the hospital’s own charity fund, but help is limited and decided case by case. Bring your passport and any insurance documents.
How long does a MediFund application take?
Usually a few working days after you submit all documents, though it can take 1-2 weeks if income proof is missing. The clock starts when the file is complete, so bring your payslips to the first appointment.
Is it safe to ignore the bill while I apply?
No. Ignoring it can send the debt to a collection agency, which reduces the hospital’s ability to help. Tell the MSW immediately and ask for a hold on the account while your application is processed.
What happens if my application is rejected?
You can appeal. Ask the MSW why it was rejected, fix the gap — usually missing documents or an income figure that needs review — and resubmit. You can also ask about a longer installment plan instead.
How much can MediFund cover?
It depends on your income, household size, and the bill size. There’s no fixed percentage. The MSW assesses each case, and MOH publishes the framework but not individual payout amounts. Ask the MSW what your specific case qualifies for.
Do I need to pay anything upfront?
You may need to pay your MediShield Life deductible and co-insurance, but MediFund can cover part of that too. Ask the MSW before paying anything large. Don’t hand over a big lump sum before your assessment is done.
Can I apply before my surgery, not after?
Yes, and you should if you know a big bill is coming. Talk to the MSW before admission. Pre-approval isn’t guaranteed, but starting early gives you more options and less stress after discharge.
Conclusion
The system is built so that no one in Singapore goes without care because of money. The key is to ask early, bring your documents, and work with the medical social worker at your hospital. They’re there to help you find the right scheme, not to turn you away.